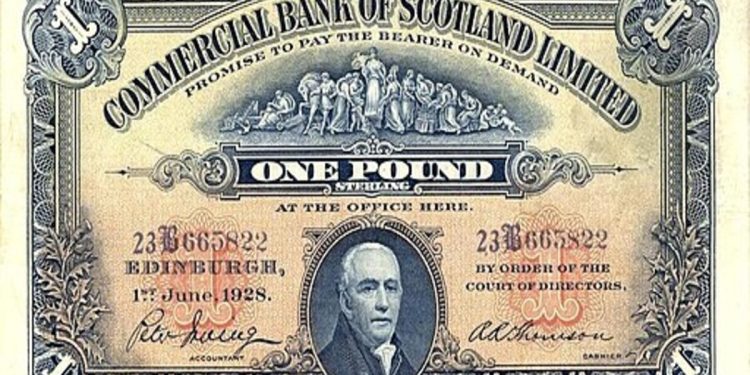

Scottish Government’s plans to issue £1.5bn in bonds (nicknamed as ‘kilts’ to mimic the term used for UK government bonds – gilts) is to be welcomed. The Scottish Currency Group (SCG) has advocated for some time now that the Scottish Government and Scottish local authorities should use the borrowing powers available to them within the UK fiscal framework to do exactly this.
The Scottish Government’s rationale
A reading of the Scottish Government report, Scottish Government Bonds Programme, makes it clear that the bond issuance is aimed at attracting foreign direct investment (FDI) and, therefore, reflects the Scottish Government’s obsession with attracting foreign capital to Scotland. However, our government seems oblivious to the fact that foreign investment results in long term outflows of funds larger than what comes in. Mostly, foreign investors invest in Scotland’s assets and resources to make profits for themselves and not for Scotland.
A key motivation for this bond programme is clearly to demonstrate credibility to financial markets in the run up to independence. This is another expression of the SNP leadership’s grand delusion about using the GBP after independence. Several economic commentators have argued that Scotland’s strong credit rating is because it is part of the UK and backed by fiscal transfers (the Barnett Formula ). These fiscal transfers will not be available after independence. So, it follows that the credit rating is likely to be much lower after independence and the yields demanded by bond markets will be much higher if Scotland continues to use the GBP after independence.
The Scottish Government is openly proud of the credit ratings it has been awarded because of its proven “fiscal discipline”. The report makes numerous references to the bond programme as a means of strengthening “fiscal discipline”; an admission that the credit ratings are based on the Scottish Government’s record in managing austerity and that continued efforts to “balance the books” are desirable in order to retain these ratings. Capitulation to austerity and to the finance markets is written large in the report.
Kilts and the bond market
Although the rating agencies have awarded Scotland a credit rating similar to that of the UK it is still likely that bond markets will demand a higher interest rate (yield) on kilts than is offered on UK gilts. Nevertheless, the usual bond market bogeyman that is invoked by scaremongers who seek to spread fear and alarm about the costs of government debt can be put back in its box.
We don’t know what maturities will be offered (1-year, 5-year, 10-year etc). But let’s suppose that the interest rate offered and accepted for a 10-year £1000 kilt is 4.5%. The Scottish Government’s liability is 10 years interest at £45 per year; £450 in total. At maturity the principal of £1000 must be repaid. The total liability is £1450. This does not change regardless of whether the kilt is subsequently traded on the secondary bond market and whether its original value/price (£1000) changes.
It is possible if £1.5bn of kilts are issued in several smaller issuances that the secondary trading of the initial tranche will influence the yield demanded on subsequent tranches. It may go up or down. The favoured option set out in the report is to issue kilts in several tranches over 5-10 years as this is seen as a means to reduce the costs of issuance. However, the risk of bond markets demanding a higher yield on later tranches could negate the expected cost savings. If kilts are to be issued to the global bond market, there is a case to issue the full £1.5bn in one tranche.
Kilts only for Scottish savers and investors
If the Scottish Government really had any long-term vision, consistent with genuine political and economic sovereignty, it would undertake, as a first priority, an assessment of demand for kilts from investors domiciled in Scotland. Ownership of kilts in Scotland would retain the interest payments within the Scottish economy. Such investors could be individual members of the Scottish public (retail investors) or large Scottish institutional investors such as the local authority LGPS pension funds or Scotland-based pension companies.
Doing this could also minimise the interest rates required to sell all of the kilts being offered. Kilts offering a short duration (say 5-year kilts) could be offered to ordinary members of the Scottish public who have savings and are likely to welcome an opportunity to see their savings helping the Scottish economy. Retail kilts could be offered via Scotland’s network of post offices.
The size of the bond issue (£1.5bn over 5 years) is vanishingly small against the massive scale of the global bond market and miniscule relative to the size of UK gilt issues (about £300bn per year). £1.5bn over 5 years could be easily absorbed by Scottish domiciled retail and institutional investors. The LGPS pension funds, for example, currently have nearly £70bn of assets under management.
Diversifying sources of borrowing is sensible
Offering kilts to diversify the Scottish Government’s borrowing sources is sensible. Until now, borrowing has been exclusively from the UK Treasury’s National Loans Fund (NLF) which charges interest at 0.11% (11 “basis points”) above the UK gilt yield. Kilts offer potential to lower the interest rates on borrowing, although this is not guaranteed given Scottish Government dependence on the bond market.
There is another good reason to reduce reliance on the NLF. Borrowing from the NLF is borrowing from a sovereign lender in that lender’s currency (the GBP). The liabilities can only be redeemed by repayment in GBP. Borrowing from private sector lenders, however, leaves it open in the future for the Scottish Government to re-denominate the bonds in Scottish currency and repay the outstanding debt in Scottish £ (Sc£). The ability to do this is derived from a principle of international law known as Lex Monetae.
However, it is highly likely that bond investors outside of Scotland will take account of “re-denomination risk” and factor this into the kilt yields that they would accept. This is because of the “Scottish independence factor”. Kilts denominated in GBP would be re-denominated in Sc£ if Scotland introduces its own currency and then chooses to redeem the outstanding liabilities in the new currency instead of GBP. This risk does not affect Scottish domiciled investors who are, therefore, less likely to demand a premium reflected in the interest rate offered on the kilts.
Credit ratings irrelevant if Scotland becomes a currency issuer
There is no need for the Scottish Government to issue bonds in order to secure a favourable credit rating that can be relied upon after independence. This is not a credible reason for the proposed bond programme. If Scotland uses its own currency after independence, today’s credit ratings and bond yields are totally irrelevant. As a currency issuer, Scotland would not need to issue bonds at all, and if it chose to do so, there would be no imperative to sell them all. This would give the Scottish Government the ability to set the interest rate offered on any bonds it issues, and the bond markets would have to take it or leave it.
Conclusion
The Scottish Currency Group welcomes the principle of Scottish Government bond issues during the period prior to independence, but kilts need only be, and should only be, offered to the Scottish public and to institutional investors domiciled in Scotland, particularly the LGPS pension funds. Bonds should not be issued in the global bond market until Scotland is independent and issues its own currency.
More on Economics: