
Scotland will inherit one of the lowest state pensions in the developed world. Supporters of Scottish independence propose to increase this significantly but even if it was doubled this will not eliminate demand for 2nd pensions. Little attention has been paid to the future of 2nd pensions.
Pension systems world-wide normally have three “pillars” and the UK is no exception. The “first pillar” is a state pension, the “second pillar” are workplace pensions and the “third pillar” are personal private pensions.
Median annual earnings in Scotland in 2024 were £38315 so even if the state pension was increased to £400 per week it would amount to just 54% of earnings. This means a significant drop in income after retirement for more than half of the population, if there is no additional income from a 2nd pension. More work needs to be done to give Scottish citizens confidence in prospects for better income security in retirement after independence.
Replacing the flat rate state pension
One possible solution would simply be to replace the flat rate state pension with state earnings- related pension. If we were starting from scratch this might make sense but the other part of the legacy of the UK pension system is the existence of 2nd pensions which have accumulated over £3tn of assets over the last 50 years or so. On a population pro-rata basis Scottish citizens’ 2nd pension assets will have a value in the region of £200-250bn. Very little of this vast pool of capital has been invested productively in the Scottish economy (nor in the wider UK).
This raises two questions; first, how can we integrate a new state pension with a new approach to 2nd pensions? Secondly, how can we direct greater investment by 2nd pension funds to support the Scottish economy? In recent years UK governments have been wrestling with the challenge of getting more pension fund investment in the UK economy without making any real progress.
A Scottish earnings-related pension system
This is the background to my proposal to create a Scottish earnings-related pension system based on a State Earnings Related Pension (SERP) and a National Pension Fund (NPF) into which existing Scottish 2nd pension assets can be transferred. My previous article described how such a NPF could be established.
The formation of the initial NPF is a relatively straight forward matter, involving auto enrolment of all new workers joining the national workforce from a specified start date, and contributions into the fund being made by those employees and their employers. Since none of the first cohort enrolling in the fund will retire for the next 40 years (this assumes full pension entitlement is based on 40 years of contributions) and no pensions will be paid out until then, the fund will grow rapidly.
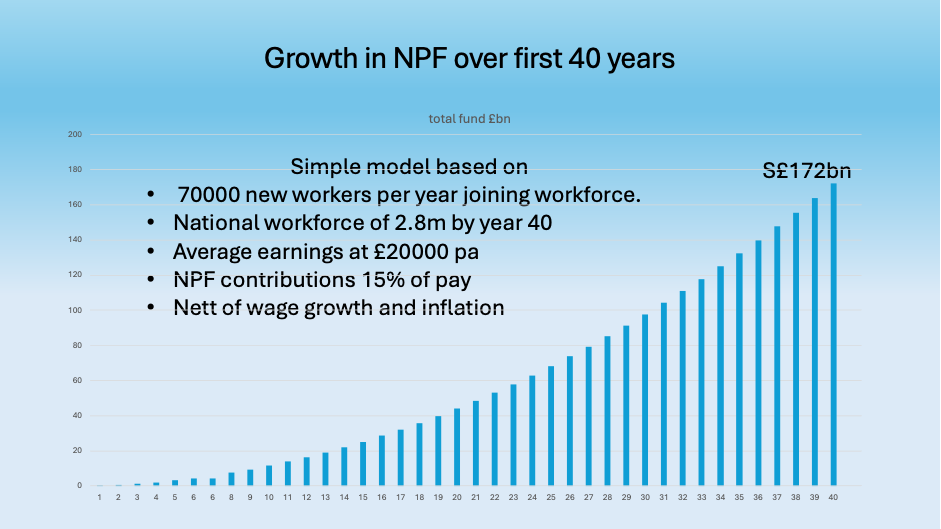
The chart below illustrates the potential growth trajectory of the NPF over 40 years based on a simple model in which an average of 70,000 new workers auto-enrol in the NPF every year, average earnings are Scottish£20,000 per year and the contribution rate is 15%. The auto-enrolled membership grows each year until it reaches 2.8m in 40 years. The value of the fund at that stage would be Scottish£172bn.
The additional capital from transferred-in- pensions will increase the fund’s value further whilst also increasing the future pension obligations to be paid by the fund. This will be considered further in the final article which will discuss issues relating to the transition period before the NPF becomes a fully mature, universal pension fund.
Since there will be only limited drawings on the growing fund to pay pensions, substantial sums will be available for investment to support the transition to a “wellbeing economy” after independence. Such investment must have the purpose of increasing the long-term productive capacity of the economy so that we can provide what our citizens need to live happily and healthily throughout their lives.
Fund structure of the NPF
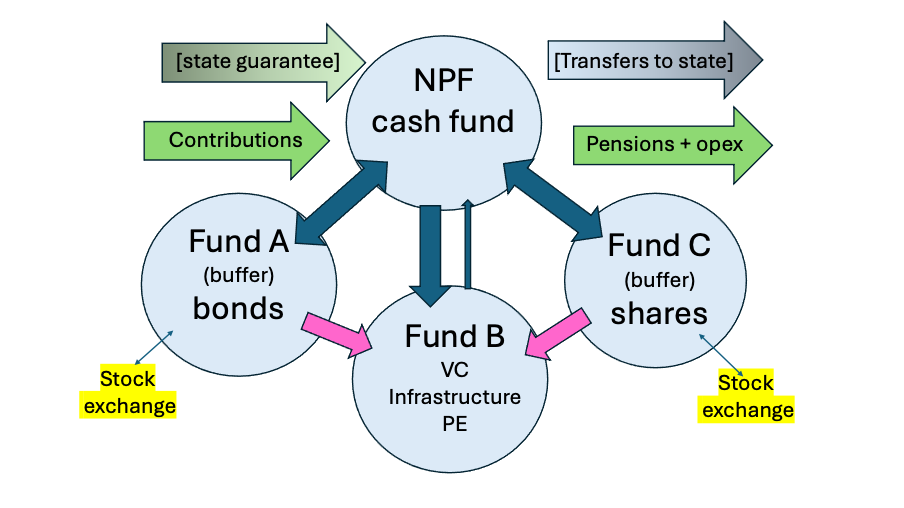
The NPF could be structured into several distinct funds as follows:
The NPF Cash Fund. This is the fund into which contribution income is credited and from which pension benefits and operating costs will be paid.
The Cash Fund would be supported by 2 buffer funds, the purpose of which are to drain off excess cash from the Cash Fund and use it to purchase government and corporate bonds and quoted shares. The financial assets held in these funds are liquid in nature and can be quickly redeemed for cash to support the Cash Fund when necessary. A third fund would be allocated cash to invest in ways that give the NPF direct ownership of infrastructure or full or partial ownership of business ventures through contract-based partnerships.
Buffer Funds (A and C)
Fund A – a buffer fund held in a variety of government and corporate bonds which earn interest and which are easily converted back into cash to support the Cash Fund if and when needed. Earned interest can be transferred to the Cash Fund if needed or to Fund B (see below). Scotland will need to have established a Stock Exchange to facilitate Fund A operations.
NPF Fund C would constitute a second buffer fund, which would be allocated to share ownership. Stock selection would be subject to rigorous criteria relating to environmental, social and governance (ESG) factors and comply with “licence to operate” conditions set out in Company Law or other regulatory frameworks derived from the socio-economic and human rights of citizens which should be established in a written Scottish Constitution, which embodies the Universal Declaration of Human Rights Universal Declaration of Human Rights). Shares will be selected with the intention to hold them for a long term and not for the purposes of speculative trading but if required some can be sold quickly to provide cash to support the Cash Fund. A Scottish Stock Exchange will be needed to facilitate the operations of this fund as well.
The Direct Investments Fund (Fund B)
Fund B would be a fund for venture capital and direct investments through contractual partnerships with private sector enterprises of all types or direct investments in infrastructure such as social housing and energy. These investments will be focused on earning a return in the form of cash flows from sharing in profits or revenues from social housing rents and energy supply.
This fund would not normally function as a buffer fund to support the liquidity requirements of the NPF Cash Fund. If there are excess funds which cannot be invested purposefully these can be remitted back to the Scottish Finance Ministry/Central Bank. This fund does not depend on a Stock Exchange or a public financial market. Investments would be aligned with the overall strategic priorities and industrial strategy of the Scottish Government but individual investment decisions would not be taken by the government but by NPF local investment offices who would be accountable to an Investment Directorate (to be discussed in the next article), which is accountable to Parliament.
Most of Fund B is likely to be invested to support start-ups and growing unlisted companies. But it is possible that contract-based partnerships could be formed with subsidiaries (or even divisions) of large, listed companies who wish to develop new products or technologies.
Ownership through Fund B, based on contractual agreements, could be a method of protecting successful Scottish businesses from takeovers by foreign investors. Contractual terms could be designed to preclude the unilateral sale of assets by one or other partner.
In the overall management of the NPF, funds can be transferred between the separate funds, taking into account the primacy of liquidity in the NPF Cash Fund, to balance income and expenditure, whilst maximising the availability of funds for investment to support the economy in alignment with the strategic priorities and industrial strategy of the Scottish Government.
How investment decisions would be made
The management of the buffer and investment funds would be governed by a statutory mandate which includes fundamental guiding principles. The next article will discuss what these would be.
More on economics: