
“There is no alternative” is a phrase, so often uttered in modern UK political and economic rhetoric, that it is generally viewed as a slogan. It is intended to defend neoliberalism, globalisation, monetarism and free markets and, literally, dismiss all other contending perspectives.
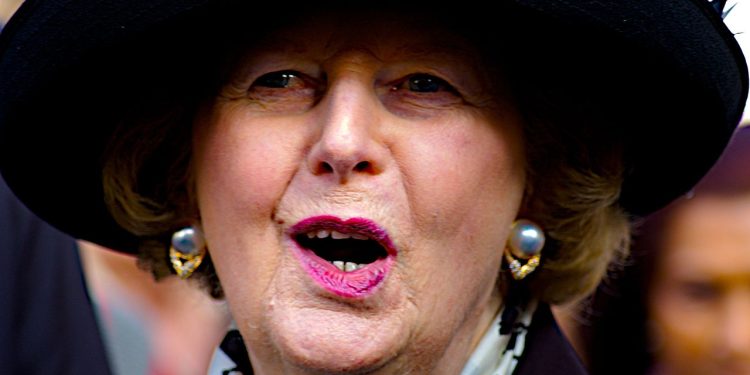
This slogan was first used by Margaret Thatcher in the 1980’s as she promoted her agenda and world-changing economic policies. However, the phrase, in this context, has been reiterated by many conservative-minded commentators and politicians over the years. Most notably David Cameron as UK Prime Minister, made this claim in defence of the austerity agenda, his government imposed, in the aftermath of the Great Financial Crisis in 2007-2008.
Confusion reigns
It is indicative of the high regard the general public has for economics as a discipline, and the low confidence people have in their ability to understand the subject. Current economic thinking is very difficult for the layman to understand. Layers of complexity and needless complication appear to be inherent characteristics in the dominant neoclassical school. It doesn’t make sense to the layman, however, it doesn’t make sense to the academic either.
Jeremy Rudd, a US Federal Reserve researcher, wrote a paper for the Reserve’s website on market expectations forecasting. It is scathing in its critique of modern economic thinking. In his Introduction Rudd states that:
“Mainstream economics is replete with ideas that ‘everyone knows’ to be true, but that are actually arrant nonsense.”
After giving a number of examples, he goes on to say:
“None of these propositions has any sort of empirical foundation; moreover, each one turns out to be seriously deficient on theoretical grounds.
“No doubt, one reason why this situation arises is because the economy is a complicated system that is inherently difficult to understand, so propositions like these – even though wrong – are all that saves us from intellectual nihilism.”
Many economists are in agreement with Rudd. They hail from a number of economic schools grouped under the banner of heterodox economics. This basically means they don’t conform to the orthodoxy, currently described as neo-Keynesian or neoclassical.
Contradiction in terms
For there to be a heterodox school at all there obviously must be an alternative. This is just as well, as current orthodox economics works for many but leaves far too many, too far behind. Conveniently for the proponents of the status quo in the Scottish independence debate, mainstream economic policy would make it very difficult to create a prosperous Scottish nation in the short term. So, thankfully, for supporters of independence (and beneficial change), Thatcher and Cameron were misinformed.
There are dozens of these alternatives. Despite this huge divergence of thought and insight, there are multiple overlaps where agreement resides, but all the schools have something different to offer economics as a whole. For them not to be considered openly, is indicative that an influential section of society is closing down the debate.
Numerous alternatives
There are institutional economists, feminist economists, ecological economists, Marxists, Austrian economists, post-Keynsians, and many more, all schools with alternatives. Differing perspectives create a model of society as viewed from all angles and constructed on wider knowledge. The current economic environment, dominated by neoclassical thinking, is based on underpinning a neoliberal ideology. The only way this is possible is through the deception framed as – “there is no alternative”.
No one economic school has all the answers. They each have different ways of attacking the questions society poses. Diverse perspectives will often interpret the questions differently due to the varying priority concerns of the schools. A cooperative effort in problem solving can spot a wider variety of obstacles and solutions, ensuring a resilient and optimal future path, and acts as a maximal check on unintended consequences.
One problem of this monoculture, created by the adamant assertion of the primacy of neoclassical economics, is the blind spots in its viewpoint. The fact that economists of this school perceive markets as all-powerful and natural results in a failure to respect sovereignty.
Concentrate on resources
Many heterodox schools understand that a high degree of sovereignty, i.e., a resilient domestic supply of the essentials for life such as energy and food, means that the nation has the ability to ride out any market interference without changing macroeconomic course. Sovereignty is a shield against market interference. A government that recognises this will always put people first as this is their electorate.
Without alternatives, there is no vehicle for evolution of thought. Without the creation of new ideas, with nature changing all around us, the only outcome is stagnation and death. Humanity must keep evolving to adapt to this changing environment and must cover all the possible bases. This requires bringing everyone into the tent, interrogating all the alternatives.
Allow the power to adapt
Economics has thousands of years of practical knowledge to learn from. There seems to have been a constant direction of travel until the 1970s. At that point, the economic discipline appears to have left the mainline. The economic train diverted onto a dead-end track with a bridge unfinished over a ravine. We need to recognise the impending danger, apply the brakes, find reverse and get economics back on track.
I’ll leave the final word to Jeremy Rudd, who in a footnote to the introduction of his paper says:
“I leave aside the deeper concern that the primary role of mainstream economics in our society is to provide an apologetics for a criminally oppressive, unsustainable, and unjust social order.”
Let us bear in mind that government should develop an economy to serve the needs of the majority of people. When the reverse is the case, as in the last fifty years in the UK, the economy serves global big business and the elites, ignoring the plight of ordinary citizens as living standards diminish.
More in economics.